In the world of agricultural commodity futures, traders often spend countless hours scrutinizing weather radars, yield forecasts, and USDA balance sheets. While supply and demand fundamentals form the core of grain trading, an external macro force frequently dictates price ceilings: the U.S. Dollar Index (DXY).
A bullish setup—such as dry Midwest weather or tight ending stocks—can quickly lose momentum if the U.S. Dollar surges. For grain traders, portfolio managers, and commercial hedgers, understanding the inverse relationship between currency strength and soybean futures (ZS) is essential for managing risk and pinpointing trade reversals.
1. The Global Currency Mechanism: Why the Dollar Matters
Benchmark agricultural futures contracts, including CBOT Soybeans, are denominated in U.S. dollars. When foreign importers—such as China, Europe, or North African buyers—purchase American soybeans, they must convert their local currencies into USD.
How a Strong Dollar Mutes Buying Power
-
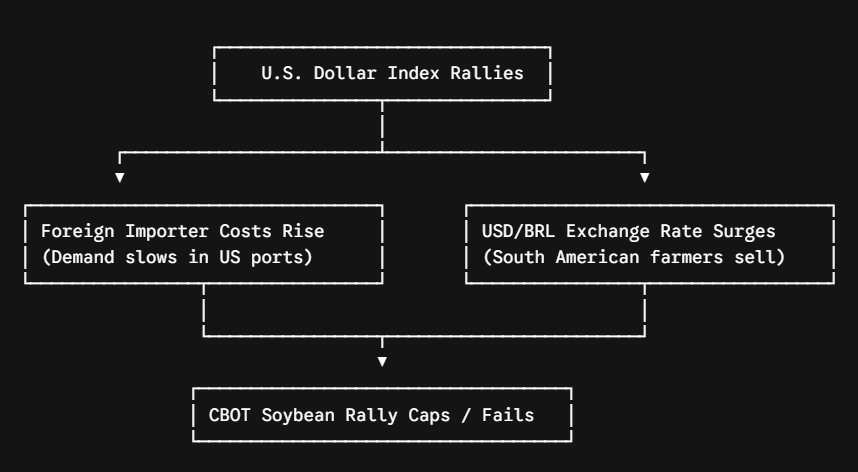
Import Inflation: When the dollar strengthens against major trading partner currencies, U.S. grains become relatively more expensive for foreign buyers, even if the futures price in Chicago remains unchanged.
-
Demand Destruction: Faced with higher local-currency procurement costs, foreign crushing plants reduce their immediate bookings, switch to alternative oilseeds, or draw down domestic reserves.
-
Export Drag: The resulting slowdown in export inspections and sales acts as an immediate headwind for CBOT futures rallies.
2. The South American Arbitrage: Real vs. Dollar Dynamics
The impact of the U.S. Dollar on soybean prices extends beyond buyer purchasing power; it directly influences competing supply from major exporters like Brazil and Argentina.
The Brazilian Real (BRL) Disparity
Brazil is the world’s leading exporter of soybeans. When the U.S. Dollar strengthens relative to the Brazilian Real (USD/BRL rises):
-
Local Currency Windfall: Brazilian farmers receive payment in U.S. dollars or dollar-linked cash prices, while paying most local operational costs in Real. A stronger dollar increases their local currency revenues per bushel.
-
Aggressive Farmer Selling: This margin expansion prompts South American producers to liquidate stored inventory and lock in forward sales, flooding the global cash market.
-
Export Discounting: Brazilian fob export premiums fall relative to U.S. Gulf and Pacific Northwest (PNW) offers, diverting global export demand away from U.S. ports.
3. Cross-Market Correlations and Macro Risk Signals
Soybean price movements rarely occur in isolation. Broad macroeconomic shifts that drive dollar strength often impact the wider commodity market simultaneously.
Key Inter-Market Drivers to Watch
-
Federal Reserve Rate Expectations: Elevated U.S. interest rates attract global capital flows into dollar-denominated assets, bolstering the DXY and exerting downward pressure on non-yielding commodities.
-
Crude Oil & Biofuel Links: A surging dollar often weighs on global energy prices. Lower crude oil prices can squeeze processing margins for soybean oil and renewable diesel, softening domestic crushing demand.
4. Tactical Strategies for Soybean Futures Traders
When a strong fundamental rally in soybeans encounters a surging U.S. Dollar, traders can deploy specific tactical adjustments to navigate the divergence:
-
Incorporate DXY Divergence Signals: If November Soybeans make a new high on weather concerns while the Dollar Index simultaneously hits multi-month highs, treat the soybean breakout with caution. Divergences often precede sharp bull-traps.
-
Utilize Currency-Hedged Options Strategies: Instead of buying outright futures during dollar rallies, consider using defined-risk options strategies—such as bull call spreads or call options—to limit downside exposure against currency-driven sell-offs.
-
Track FOB Export Differentials: Monitor Paranaguá (Brazil) vs. U.S. Gulf export premiums. Widening discounts in Brazilian cash offers signal that dollar strength is actively redirecting global trade flows.
Summary: Balancing Fundamentals with Macro Realities
A tight supply-and-demand balance sheet lays the groundwork for a soybean rally, but macro currency forces dictate whether prices can maintain their gains. By pairing USDA balance sheet analysis with a clear eye on currency dynamics, grain traders can better anticipate market tops, protect capital, and uncover high-probability opportunities across the ag complex.